Elliott has done almost everything a flotation requires except persuade investors to pay the price it wants.
Back in February TNPS reported that Elliott Management, owner of Waterstones since 2018 and of Barnes & Noble since 2019, had begun sounding out advisers for an IPO that would create the first publicly traded bookselling stock of scale.
Banks might be appointed early in 2026, I noted, London was favoured, and the April year-end made the second half of 2026 the earliest realistic window. That was the plan on paper.
Eight months on, as TNPS emerges from the Summer of Darkness, we can safely say the IPO hasn’t happened yet and will not happen this year. Leaving the all-important question, will it happen at all?
The story since February
• 26 February. Bloomberg reported that Elliott was seeking London IPO pitches from banks, with Rothschild already advising. A US listing was still on the table.
• April. Sky News reported Goldman Sachs and JPMorgan among the banks hoping to be hired, Morgan Stanley in the running for a senior role, and a valuation of around £2bn for the bookseller. It also warned that Middle East market volatility could push the float into next year.
• 7 May. Bloomberg reported that Elliott had lined up Goldman and JPMorgan to arrange a combined London listing of the two chains. This is the moment the story moved from sounding out advisers to choosing them.
• 1 July. Michael Roney, chairman of Next and former chief executive of Bunzl, became non-executive chairman of Waterstones Barnes & Noble Ltd, the holding company. It followed a headhunter search that Sky had reported earlier in the year.
• 13 July. Bloomberg reported that Waterstones was among a group of UK listing hopefuls considering deferral to 2027. Citi’s head of UK investment banking was quoted saying most candidates would now wait, and Waterstones was said to be eyeing early 2027, after Christmas trading.
• Autumn. FT-sourced roundups now list Waterstones among the London listings that have been postponed.
Two cautions. First, the postponement reports name Waterstones; in what TNPS has seen, nobody has spelled out whether the combined float, with Barnes & Noble, is deferred as a single unit. Second, there is no filing, no prospectus and no announced date. Delayed is not the same as abandoned. Third, keep in mind Sky News, per above, warning that Middle East market volatility could push the float into next year. If Middle East market volatility is a factor, then we might have to say goodbye to 2027 too.
The View From The Beach
A turnaround and an investment are different things. A retail turnaround is judged on whether the shops work. An IPO is judged on whether the cash flows justify a price. Elliott Management, with James Daunt, has demonstrated the first beyond reasonable argument. The market is still calculating the odds on the second point.
Daunt has described Waterstones as a steady, predictable, dividend-paying retailer in the mould of Next, and the chairman Elliott has just installed is by no coincidence the chairman of Next. I read that as the real pitch: not a growth story but an income stock for pension-fund-style money. Because here’s the thing: Income investors pay for certainty, and in a nervous market certainty is exactly what an IPO cannot supply.
“Pure-play” was generous. My own February piece used the phrase. Because the holding company is not purely a bookseller: alongside roughly 712 Barnes & Noble and 320 Waterstones shops it includes 107 Paper Source stationery and gift stores. Whether Paper Source goes to market inside the maybe-maybe not float is a question for any prospectus, and “bookselling stock” may be an optimistic label for what investors would actually be buying.
Publishers should be looking closely at that, because the narrative as stands tends to blur books and gifts. That matters to us in the supply chain, and to the prospective investors. It’s just one of many things we need to be cautious about when celebrating the book boom Daunt likes to take credit for.
Revival or redistribution? The February post noted the argument that a float validates a BookTok-driven revival in print reading. TNPS agreed on the counterweight to Amazon but doubted the revival claim, and nothing since changes that. Store counts measure one company winning sites and shelf space, including by buying independents such as Tattered Cover and Books Inc., which is consolidation as much as category growth.
Gross openings also overstate net expansion wherever relocations and closures are in the mix. Us publishing folk like to get weak-knee and fanciful hen we hear abut book stores opening, but Daunt is a company seller, not a bookseller per se. He’s selling a company that happens to sell books.
This is the same guy who sold Amazon Kindle devices in Waterstones stores in direct competition with the Waterstones ebook store. If Daunt could sell his grandmother, she’d be on the shelf. He even ditched the apostrophe in Waterstone’s, FFS!
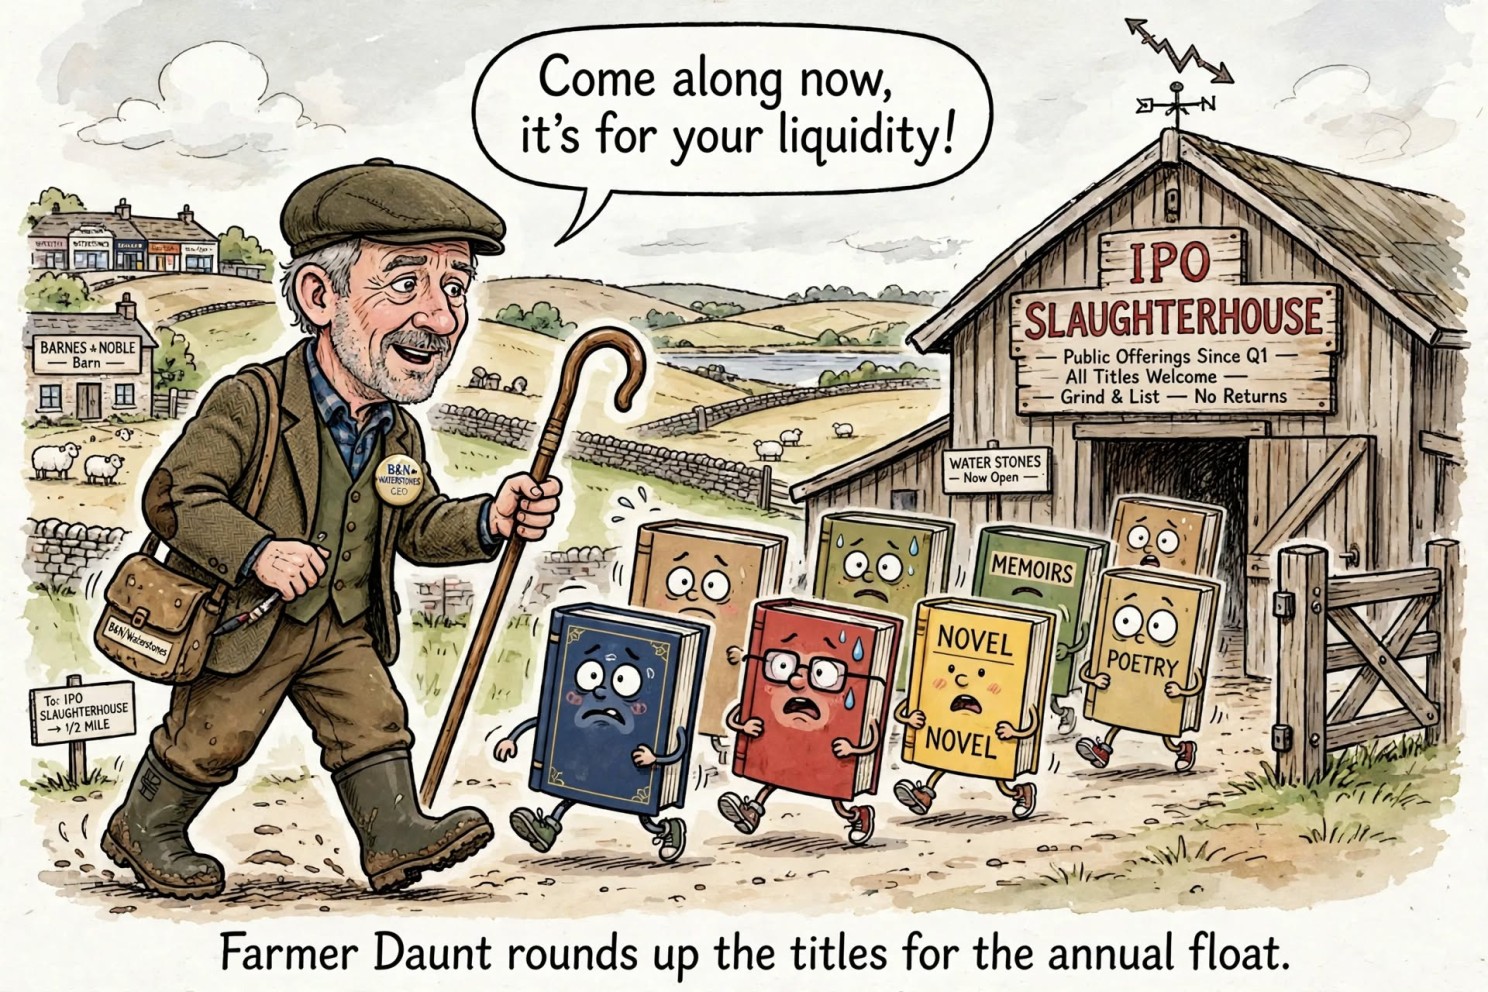
James Daunt I think of nowadays as Farmer Daunt. Just as a farmer looks after his precious livestock right up until the day they are slaughtered, so Daunt looks after his shelf-stock.
An IPO prospectus will have to show like-for-like sales and net store numbers, and those, not the opening programme, will tell investors – and the rest of us if we get to see the numbers – whether the market is growing or merely being redistributed.
Daunt’s model meets shareholders. The boutique-at-scale approach depends on store-level autonomy over buying and display. Daunt has made much of this as explaining the undeniable successes of B&N and Waterstones, and hype and exaggeration go hand in hand.
But… Public shareholders tend to prize consistency and predictable earnings. Daunt told the BBC earlier this year that a listing felt like “an inevitability” and a better outcome than being flipped to another private-equity owner, which strikes me as a lesser-evil argument rather than an enthusiastic one.
Bottom line: Elliott wants out. Hedge funds are in the business of selling businesses, and Elliott wants new fish to fry. Daunt saw an IPO as a fast-buck maker to satisfy all-comers. Donald Trump had other ideas. From Iran to tariffs, market uncertainty scares the shit out of IPO investors. And Trump could well be around another two years, making even a 2028 IPO unlikely.
Lately Farmer Daunt has declined to discuss a listing, and Fortune’s August profile said it remained unclear when or whether the company would go public. The Wall Street Journal reported in May that at one point he had the entire corporate staff reapply for their jobs and let a few dozen go.
Reality is, the decentralised shopfloor sits on a very tightly run centre, and a public float will put that centre under a microscope.
What to watch
• A notice of intention to float, which would be the first formal sign that the early-2027 window is holding. I’d rate that probability very low right now.
• Combined or Waterstones first. The deferral reports name only Waterstones, and the order and structure of any listing will say a lot about how confident Elliott is. Or how desperate they are to make and break.
• The valuation. Reports have ranged from around £2bn for the bookseller to more than £3bn for the combined group. If Elliott is waiting, it is waiting for a number. Whether it accepts a lower one is going to be the real test.
• Like-for-like sales and net store numbers, rather than headline openings.
The delay is not evidence that the bookselling turnaround has failed. But it is evidence that running good shops and executing a good exit are different skills, and that Elliott has so far proved only one of them.
As things stand, I would not be surprised if the IPO plan were put out to pasture, and another hedge fund – maybe KKR – stepped in to give Elliott the exit it wants. Either way, Daunt wins. And hopefully publishing will continue to cash in too.
Tis post first appeared in the TNPS LinkedIn Analysis Newsletter.